September 2026 Equipment Market Update: Values Firm, Volume Freezes
This month's deeper read comes from a recent episode of the Successful Farming podcast, where Tractor Zoom's Andy Campbell and machinery expert Ryan Roossinck broke down where the used market sits heading into fall. Their throughline matches what the post-September numbers in this report show. Values are holding or even firming, while volume stays thin and the real opportunities are opening up in specific corners of the market.
The clearest pattern is a market splitting by age and spec. Late-model, tech-enabled equipment is holding its value while last-generation iron steps down harder, and well-maintained older equipment is bringing surprisingly strong money at farm auctions. Corn back above $5 has buyers more optimistic, but with the crop not yet in the bin, most are still waiting to commit.
Some takeaways from this month's Successful Farming podcast:
- Late-model self-propelled sprayers are holding value: Tech-enabled machines (roughly $200K and up) are staying firm while older generations erode, a clearly bifurcating market.
- Class 7 & 8 combines have found a new normal, with supply down about 10% year-over-year and prices stabilizing rather than falling.
- High-horsepower row crop tractors are posting strong auction values on thin volume, as buyers priced out of a tight retail market compete for the few good pieces that reach auction.
- 4WD tractors remain the big question mark: The newest units are holding close to expectations, but last-gen models are stepping down, which Ryan sees as a buying opportunity this fall.
Listen to the full Successful Farming podcast episode with Andy and Ryan for the complete breakdown, including standout sales from a recent retirement auction and why 35- and 40-foot draper headers are outperforming 45-footers. And find dozens of stories around the machines you sell and care about on Ryan’s Interesting Iron blog.
Finishing 2026 strong: Join our fall market webinar
Before the category numbers, if you make buy-sell, capital, or credit decisions, this one's for you. Andy Campbell is sitting down with Meridian Ag Advisors' Chief Ag Economist Wesley Davis on October 21 at 11:00 AM CT (live on Zoom) for a year-end macro read and an early look at 2027. They'll dig into farm income, trade, the election, and the unfinished Farm Bill, as well as the two questions underneath all of it: Who's going to buy equipment in 2027, and who's going to be able to pay their loans. Save your seat.
A note on this month's numbers
Every core category below reports five metrics (Inventory Volume, Aged Inventory (360+ Days), 60-Day Sales Velocity, Turn Rate, and Auction Values) shown year-over-year for a more apples-to-apples comparison. All metrics are sourced from Tractor Zoom Pro’s dealer and auction marketplace data.
Utility tractors (100–174 HP)
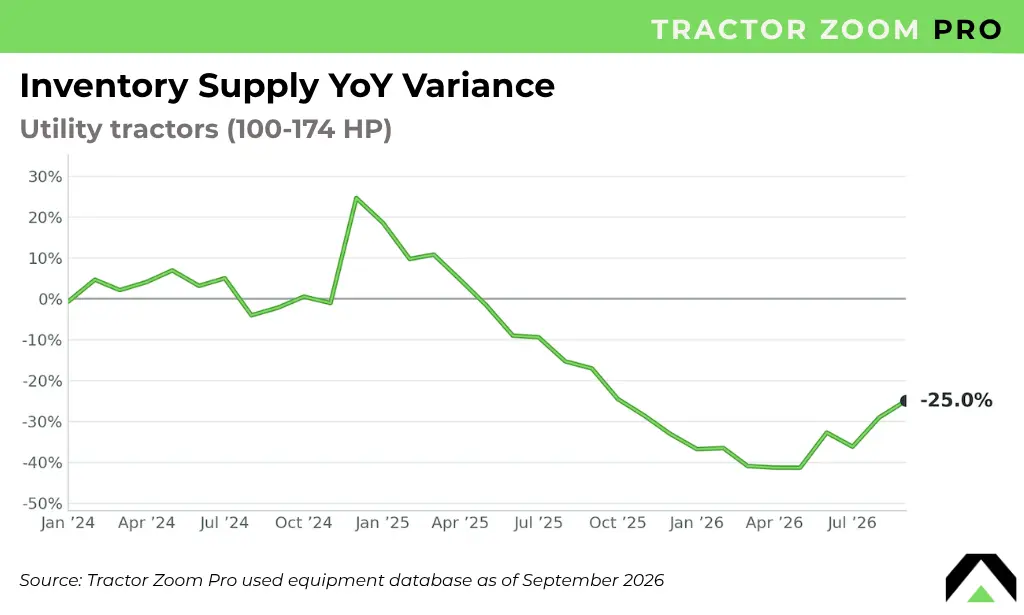
Supply kept thinning faster here than in most other categories, and turnover slowed to its weakest reading of the year. Auction values, though, held just above last year. The resilience that carried this class through 2025 on the back of a strong cattle market has faded, with high feeder prices pulling cattlemen's dollars elsewhere. But scarce supply is still keeping values from slipping.
- Inventory Volume: -25% YoY
- Aged Inventory (360+ Days): -32% YoY
- 60-Day Sales Velocity: -81% YoY
- Turn Rate (3-Month Avg.): -40% YoY
- Auction Value Avg.: +2.6% YoY
Small row crop tractors (175–299 HP)
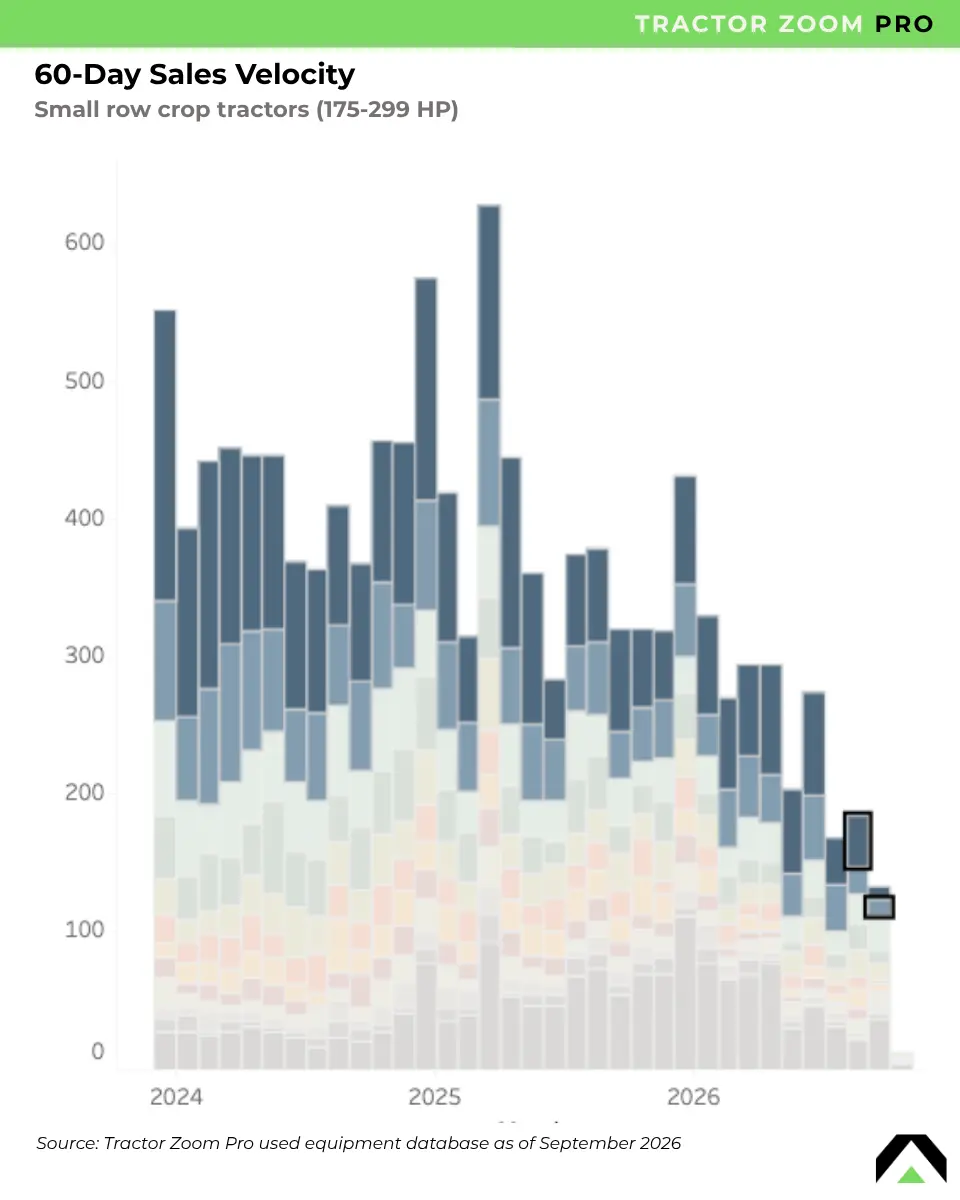
Still the softest tractor class on turnover, with velocity and turns both falling further than anywhere else. The counterweight is at auction, where values again firmed over last year. This is consistent with thin dealer movement nudging more buyers into the auction ring, where fewer options and more eyeballs keep prices supported.
- Inventory Volume: -14% YoY
- Aged Inventory (360+ Days): -27% YoY
- 60-Day Sales Velocity: -82% YoY
- Turn Rate (3-Month Avg.): -44% YoY
- Auction Value Avg.: +6.4% YoY
Large row crop tractors (300–424 HP)
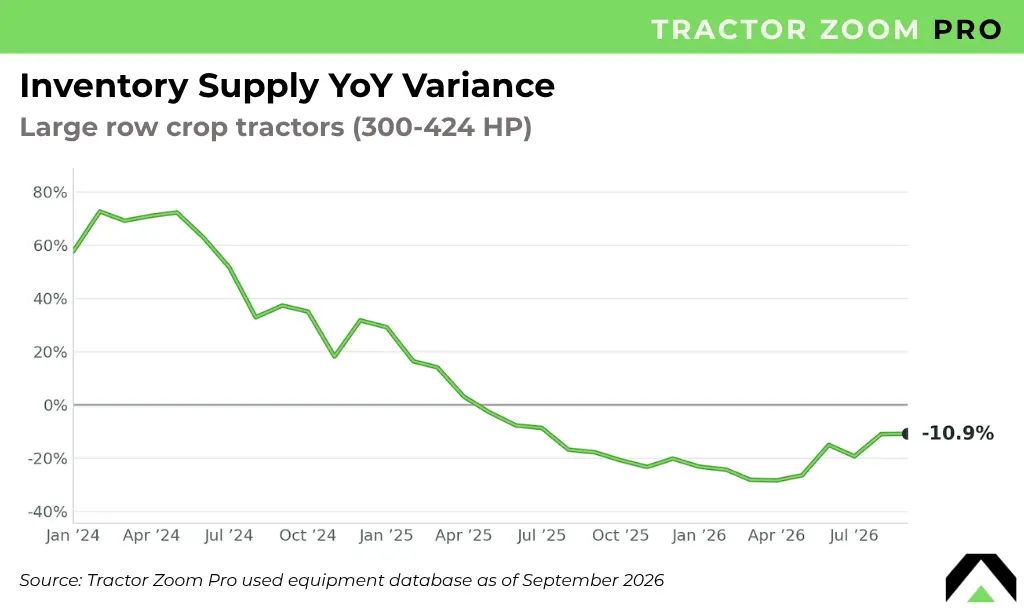
This category represents a clear example this month of the theme Andy and Ryan flagged: Strong values, thinner volume. Retail turnover slowed sharply, but late-model high-horsepower iron is holding its value and auction prices ran well above last year, as buyers squeezed out of a tight retail market compete for the good pieces that do reach auction.
- Inventory Volume: -10% YoY
- Aged Inventory (360+ Days): -16% YoY
- 60-Day Sales Velocity: -59% YoY
- Turn Rate (3-Month Avg.): -32% YoY
- Auction Value Avg.: +22% YoY
4WD tractors (425+ HP)
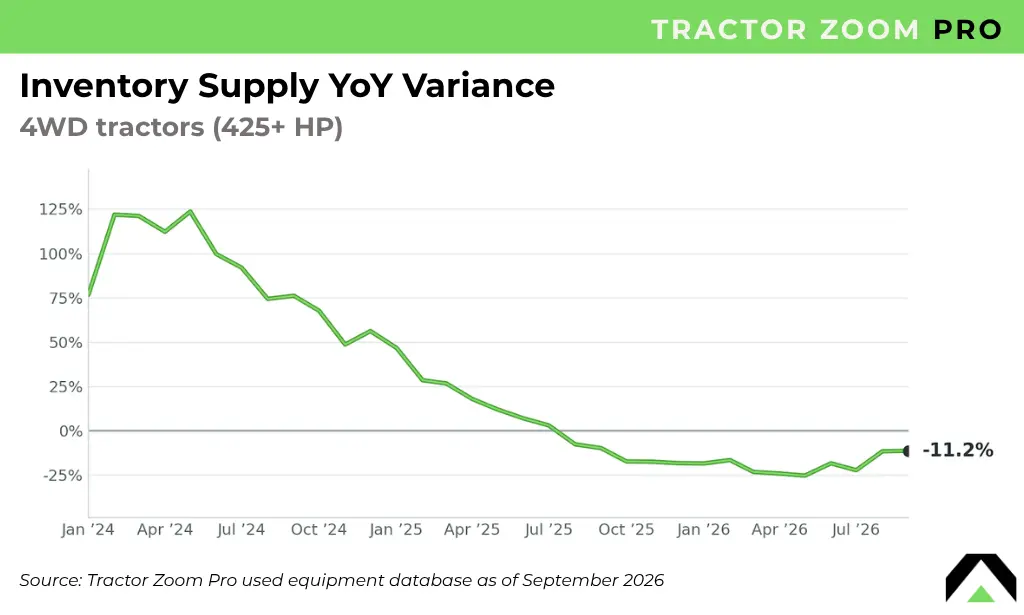
Still the market's big question mark, and the lone category with auction values below last year. Supply remains heavy relative to demand, and turnover continues to slide. The nuance Ryan drew out was that the newest units are holding close to expectations while last-generation high-horsepower tractors step down harder, which is exactly why he sees opportunity here for patient buyers this fall.
- Inventory Volume: -11% YoY
- Aged Inventory (360+ Days): -14% YoY
- 60-Day Sales Velocity: -60% YoY
- Turn Rate (3-Month Avg.): -27% YoY
- Auction Value Avg.: -4.4% YoY
Combines (Class 7 & 8)
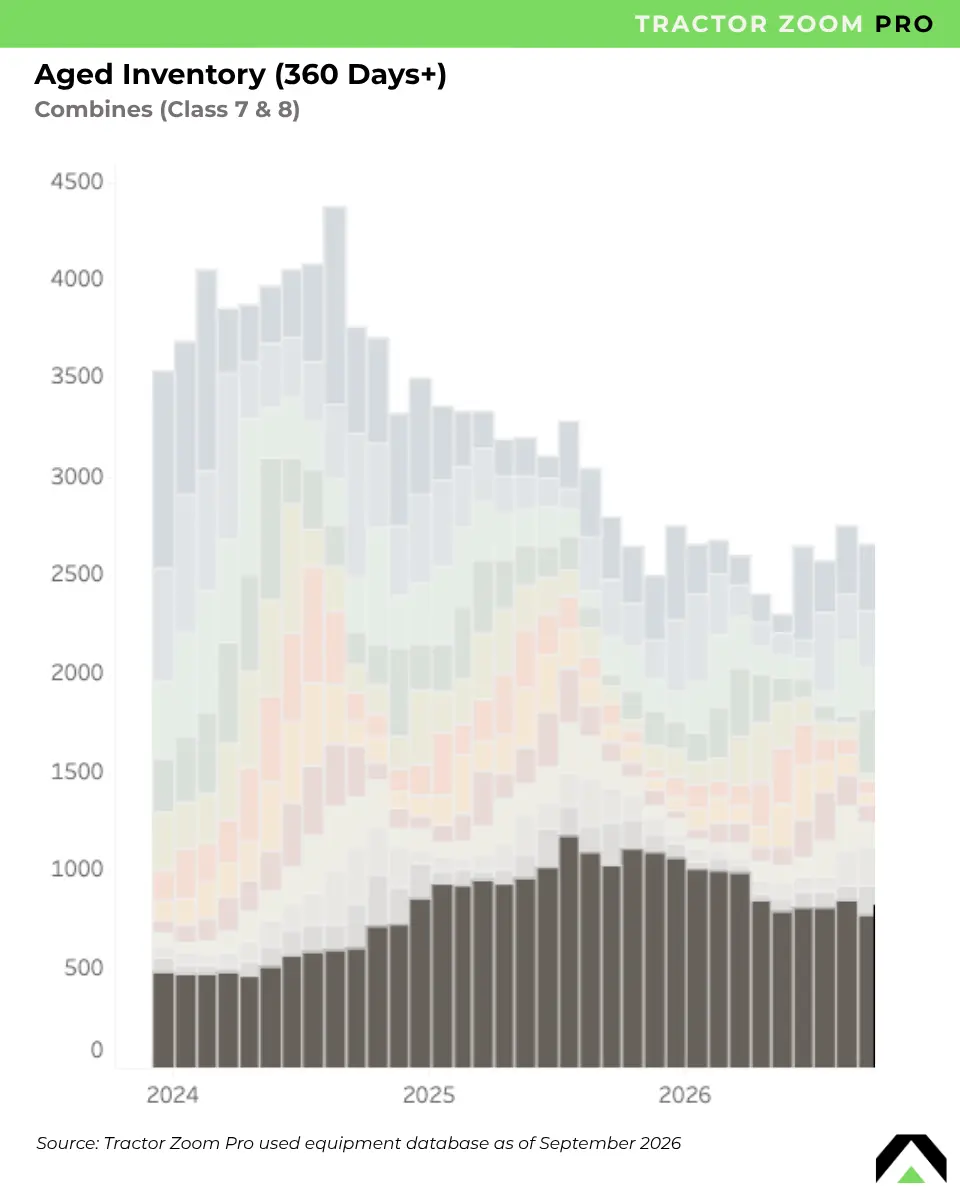
The standout recovery story. After a rough run at auction earlier in the year, Class 7 and 8 values swung back above last year. This is the "new normal" Ryan described, with supply down meaningfully and prices stabilizing rather than collapsing. Turnover stayed slow heading into harvest, as it typically does, but the pricing picture looks healthier than it has in months.
- Inventory Volume: -4.7% YoY
- Aged Inventory (360+ Days): -24% YoY
- 60-Day Sales Velocity: -72% YoY
- Turn Rate (3-Month Avg.): -26% YoY
- Auction Value Avg.: +14% YoY
Self-propelled sprayers
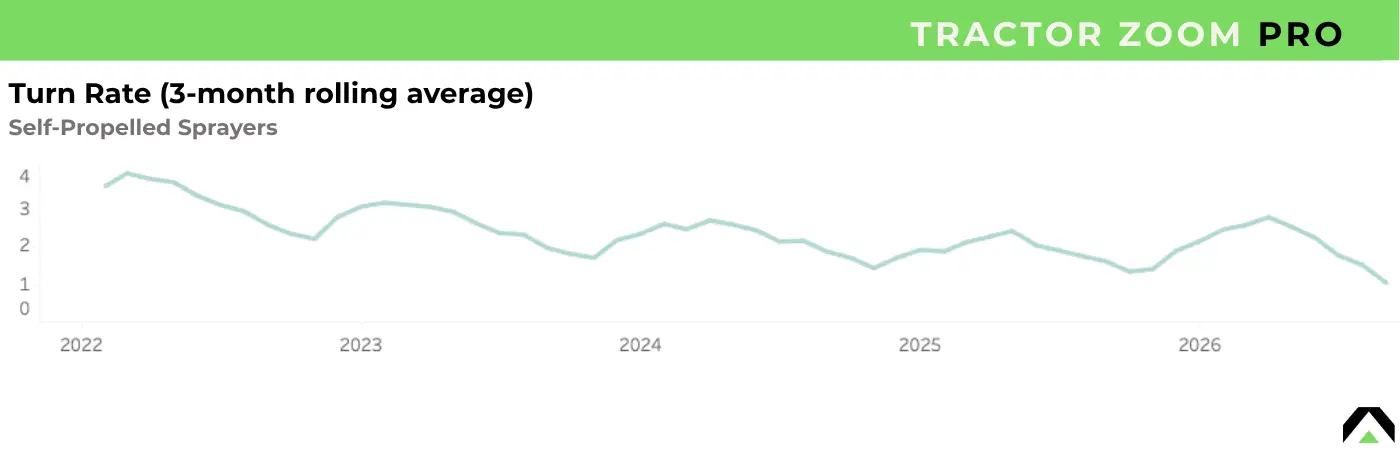
A bifurcated market, as Andy and Ryan put it. Late-model, tech-enabled sprayers are holding firm while older generations erode, and the blended auction read landed essentially even with last year. Supply thinned and aged units cleared, but turnover slowed more than almost anywhere. Even considering this is the off-season for sprayers, this is still the softest turn reading this category has seen in at least five years.
- Inventory Volume: -20% YoY
- Aged Inventory (360+ Days): -35% YoY
- 60-Day Sales Velocity: -42% YoY
- Turn Rate (3-Month Avg.): -60% YoY
- Auction Value Avg.: FLAT YoY
Planters (all rows)
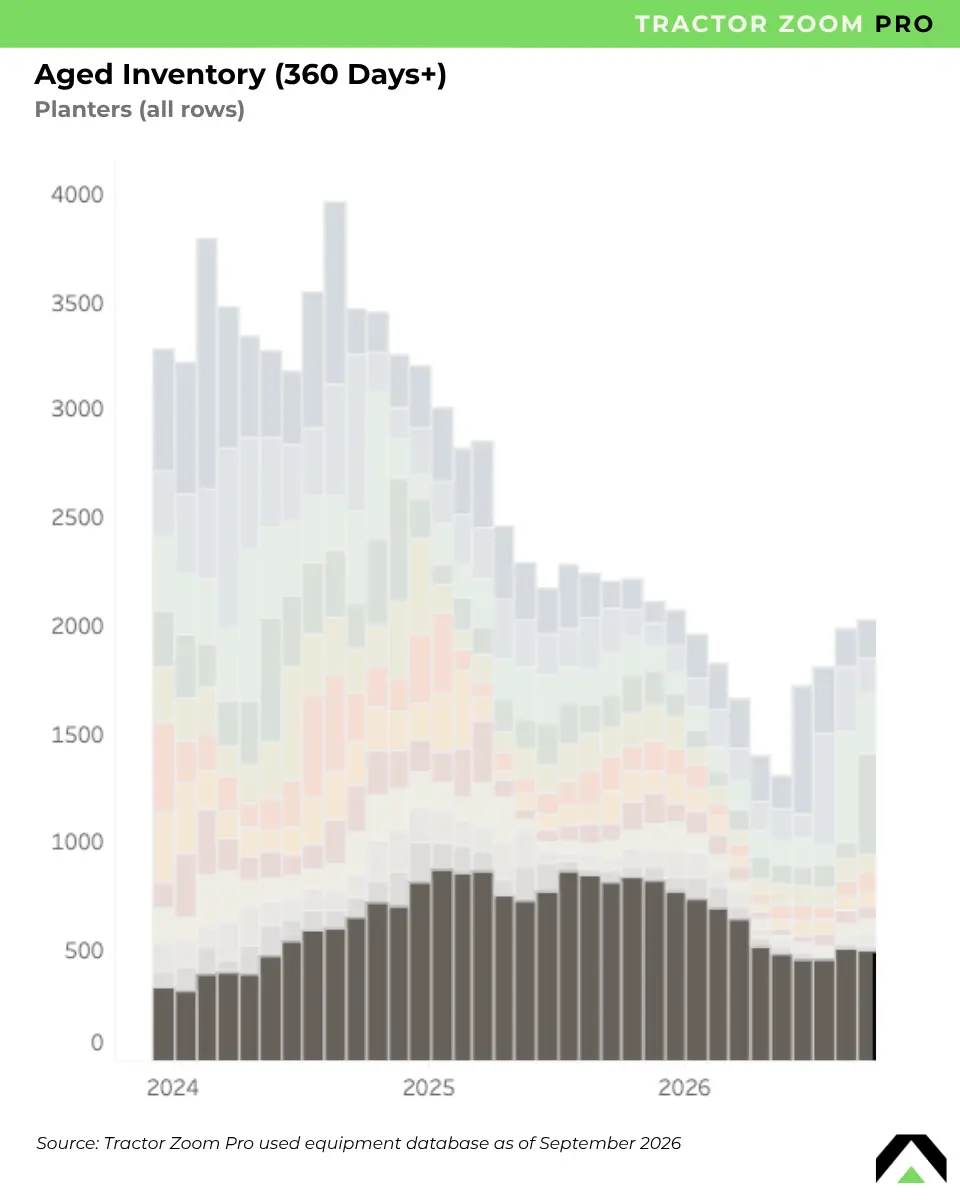
Planters keep clearing aged iron faster than almost any category, and auction values held just above last year. A strong early-order season this past spring (the first real break in a multi-year planter-sale drought), plus a wave of used trade-ins, suggests the category has bounced off its bottom, even as in-season turnover stayed slow. A lot will be determined in the coming post-harvest sales data.
- Inventory Volume: -7.9% YoY
- Aged Inventory (360+ Days): -38% YoY
- 60-Day Sales Velocity: -41% YoY
- Turn Rate (3-Month Avg.): -35% YoY
- Auction Value Avg.: +2.5% YoY
Definitions & data sources
All equipment data and market trends presented in this report are sourced from Tractor Zoom Pro's dealer and auction marketplace database, which tracks equipment listings, transactions, and inventory activity across the U.S.
- Inventory Volume: The total number of equipment units actively listed for sale across the tracked dealer network at the time of reporting.
- Aged Inventory %: The percentage of active inventory that has been listed for 360 days or longer, indicating the share of inventory experiencing extended selling timelines.
- Turn Rate: A measure of how quickly inventory is selling, calculated using a three-month rolling average of unit retail sales volume relative to available inventory. Higher turn rates indicate faster inventory movement and stronger market absorption.
- 60-Day Sales Velocity: The number of units in a given category that sold within 60 days or fewer of their initial listing date during the reporting month. Higher numbers indicate stronger early demand and healthier sell-through.
- Auction Value Avg.: The average sale price for a given category, with major outliers excluded (e.g., older and custom equipment that fetched much higher or lower prices).
The bottom line
September sharpened a split that's been forming all year. On the pricing side, the picture tells a story of quiet healing: Auction values firmed year-over-year in nearly every category, combines found a new normal, and only 4WD tractors are still underwater.
But the movement side froze, with velocity and turns hitting their weakest marks of the year across the board, as buyers still wait to see what comes out of the field. Corn back above $5 has lifted sentiment, but as Andy put it, it's "not in the bank yet." The categories to watch into harvest are 4WD tractors, where patient buyers may find the fall's best opportunities, and anything tied to post-harvest cash. If $5-plus corn holds, the loose supply still floating around could tighten quickly.
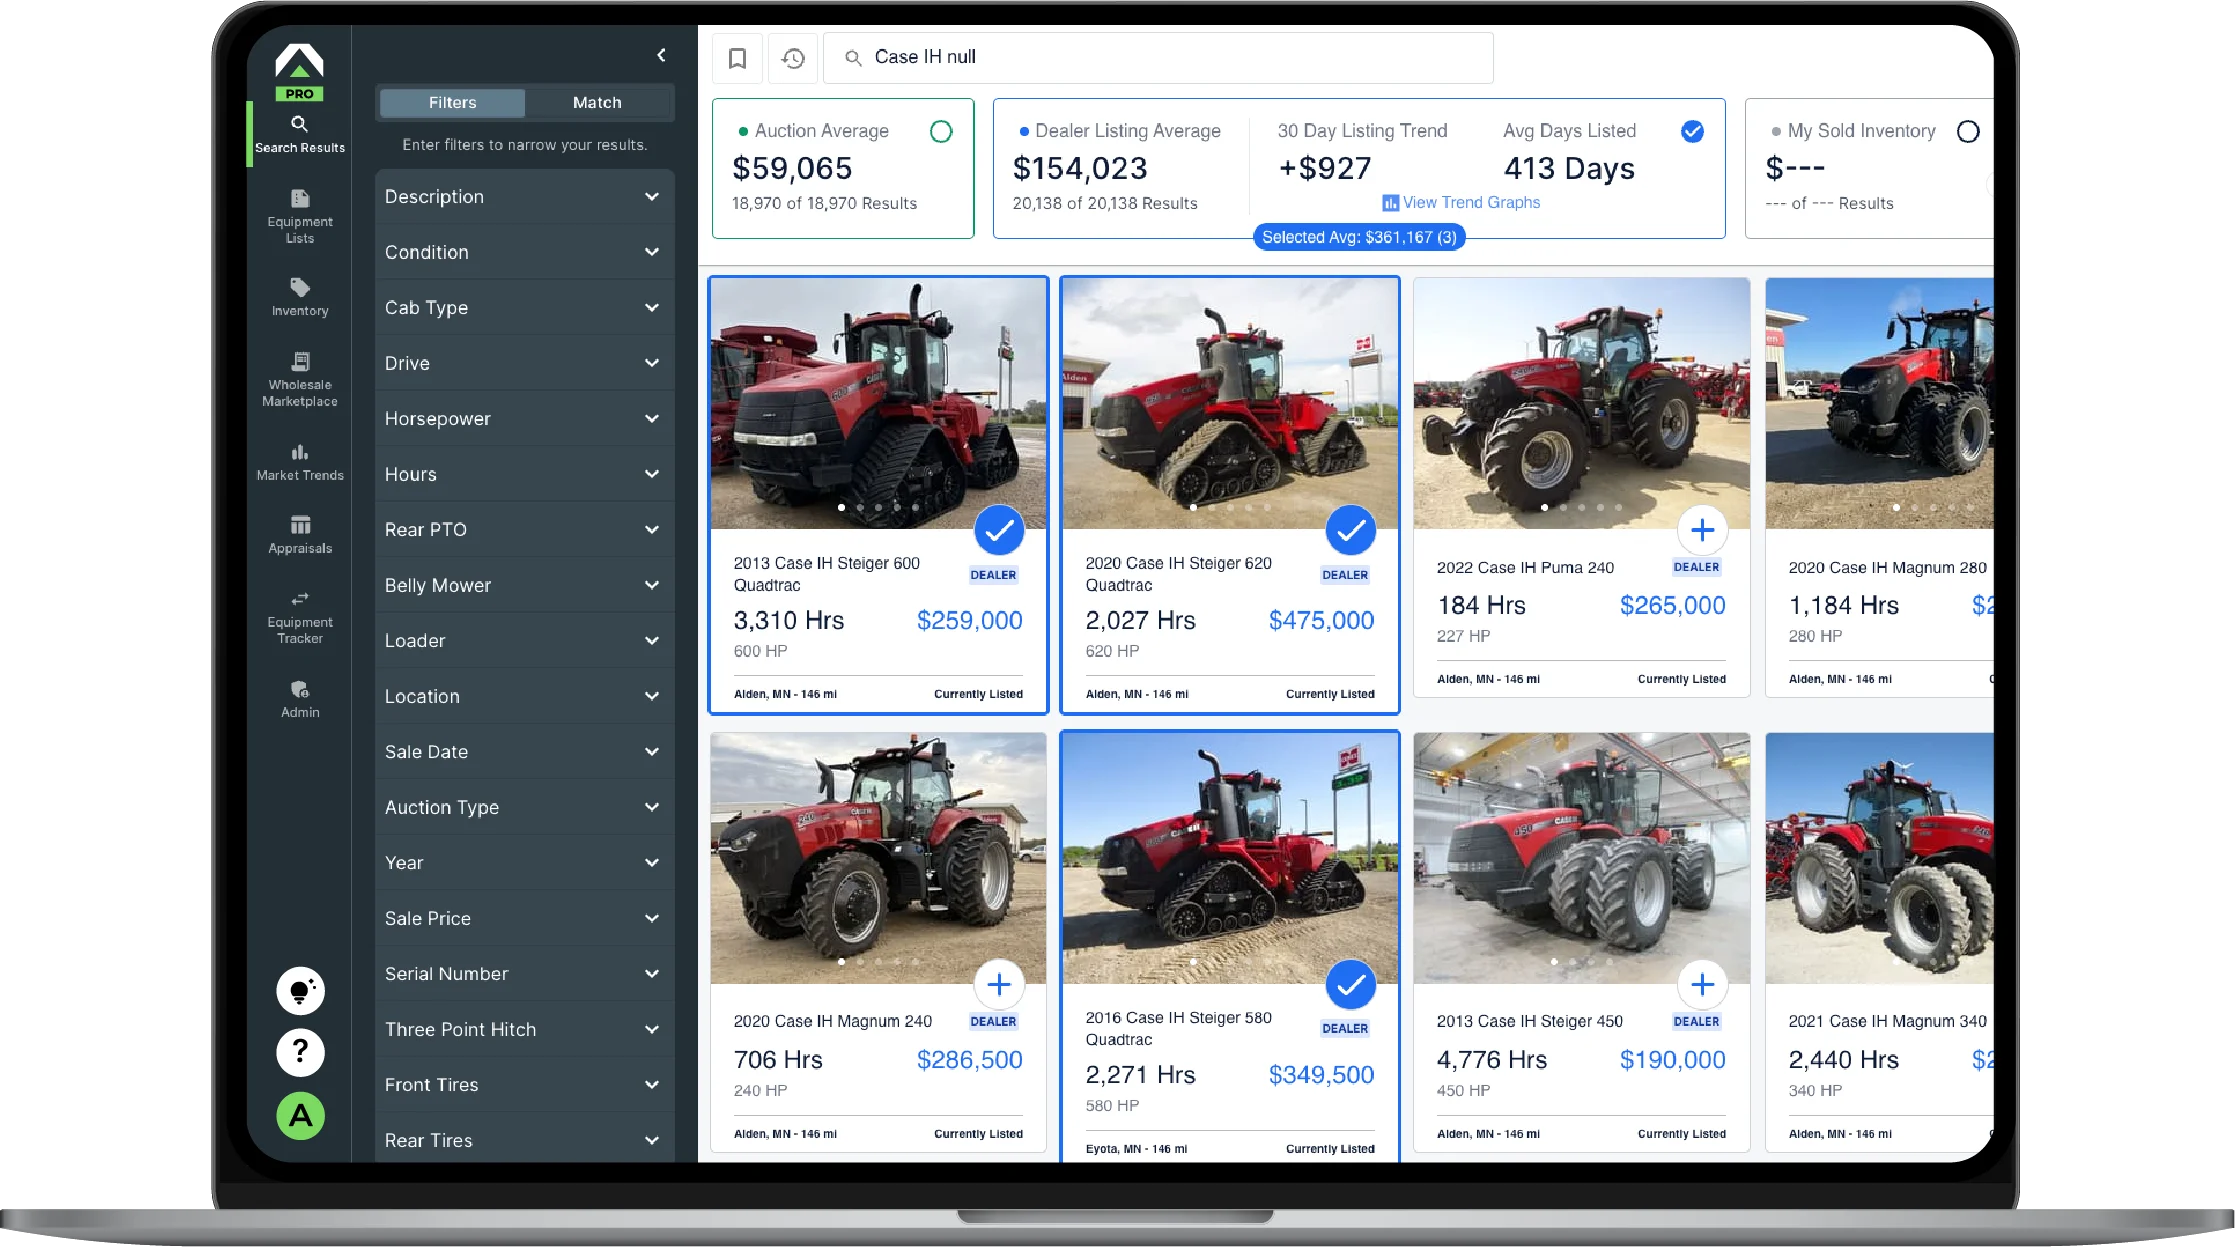
Not yet submitting your sold data through Tractor Zoom Pro? It takes minutes to set up and gives you access to the real-time comps driving these decisions. If you're already a Tractor Zoom Pro user, reach out to your Customer Success Manager to make sure you have access to this data source.
To get market insights like these delivered to your inbox each month, sign up for our free newsletter.
Join the future of ag & heavy equipment sales
Take a guided tour of Tractor Zoom Pro and Anvil Pro to discover how wider margins and faster turns are just a few clicks away.