October 2026 Equipment Market Update: Values Climb as the Supply Gap Closes
October weather was widely suitable for harvest, and the numbers reflect that. Buyers were in the cab, not on the lot, and sales slowed in every category we track. Underneath that slow month, though, two things moved in a direction worth paying attention to.
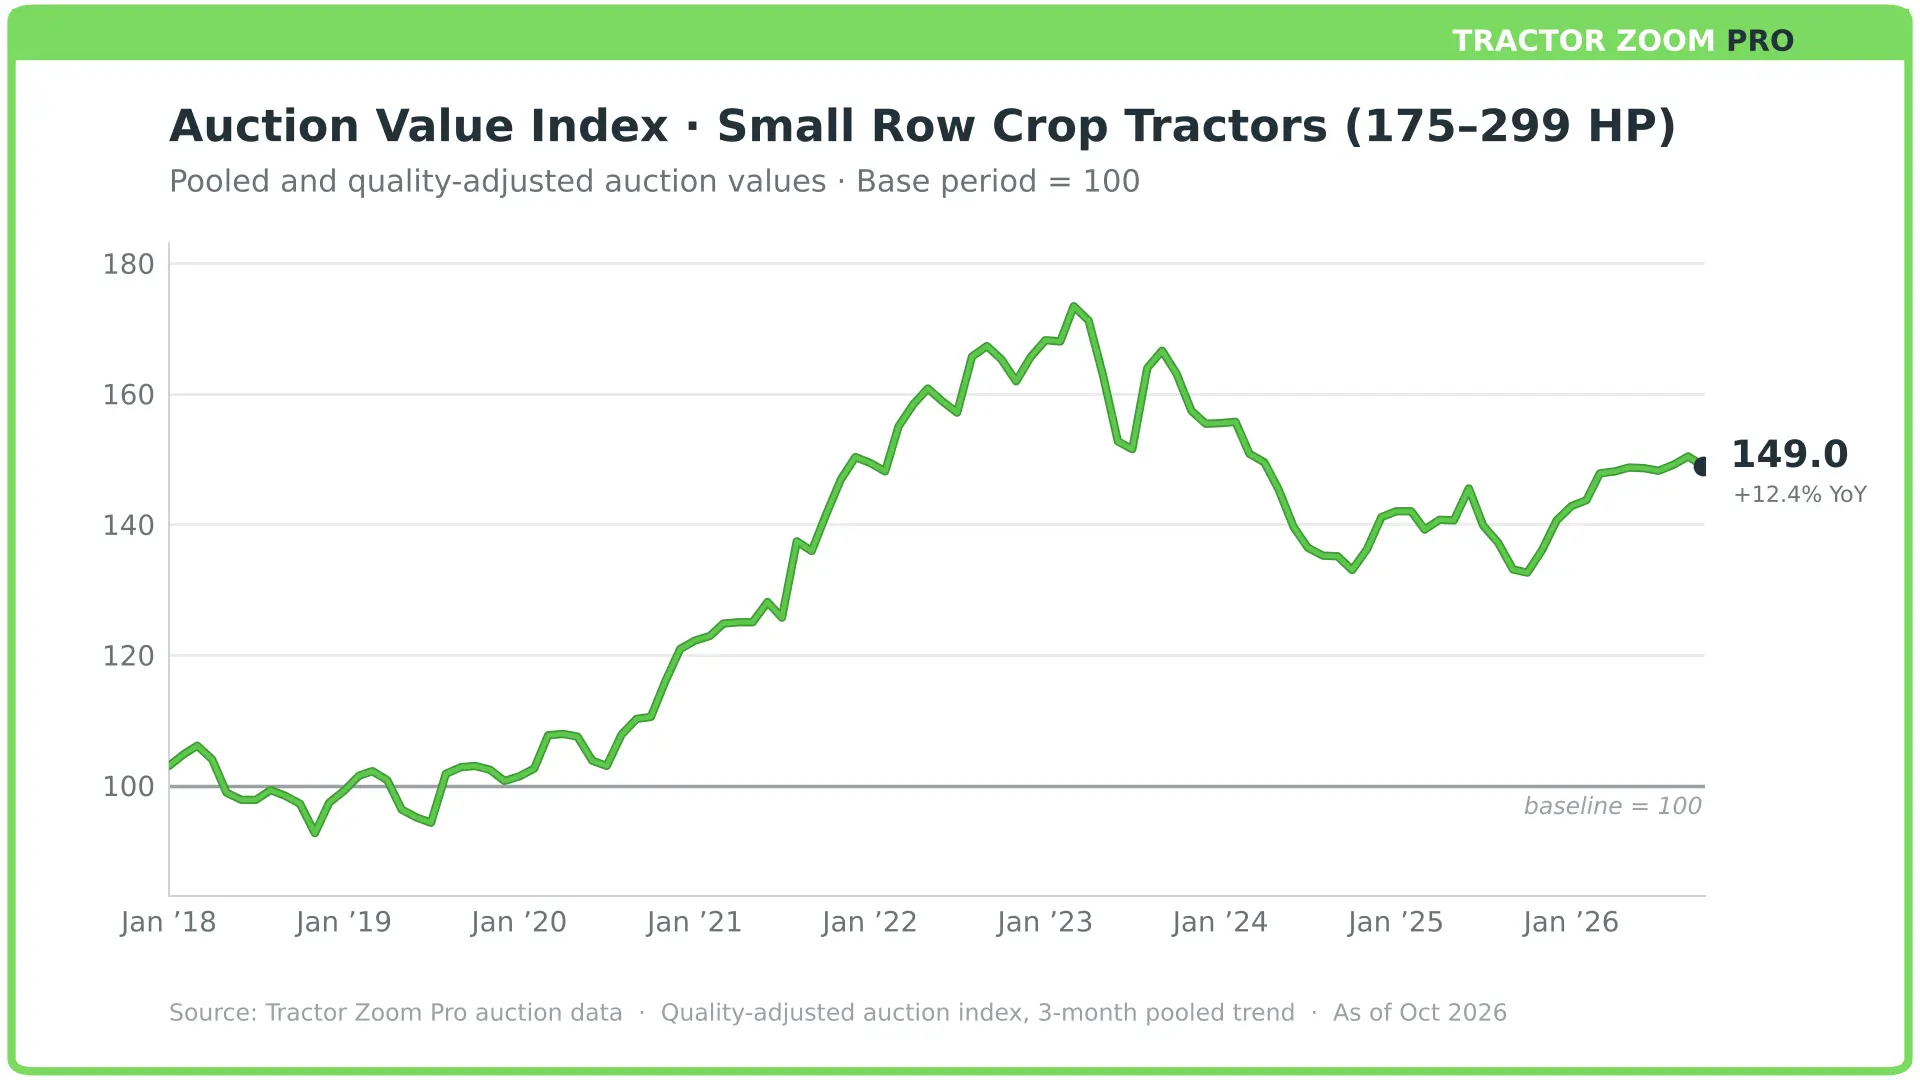
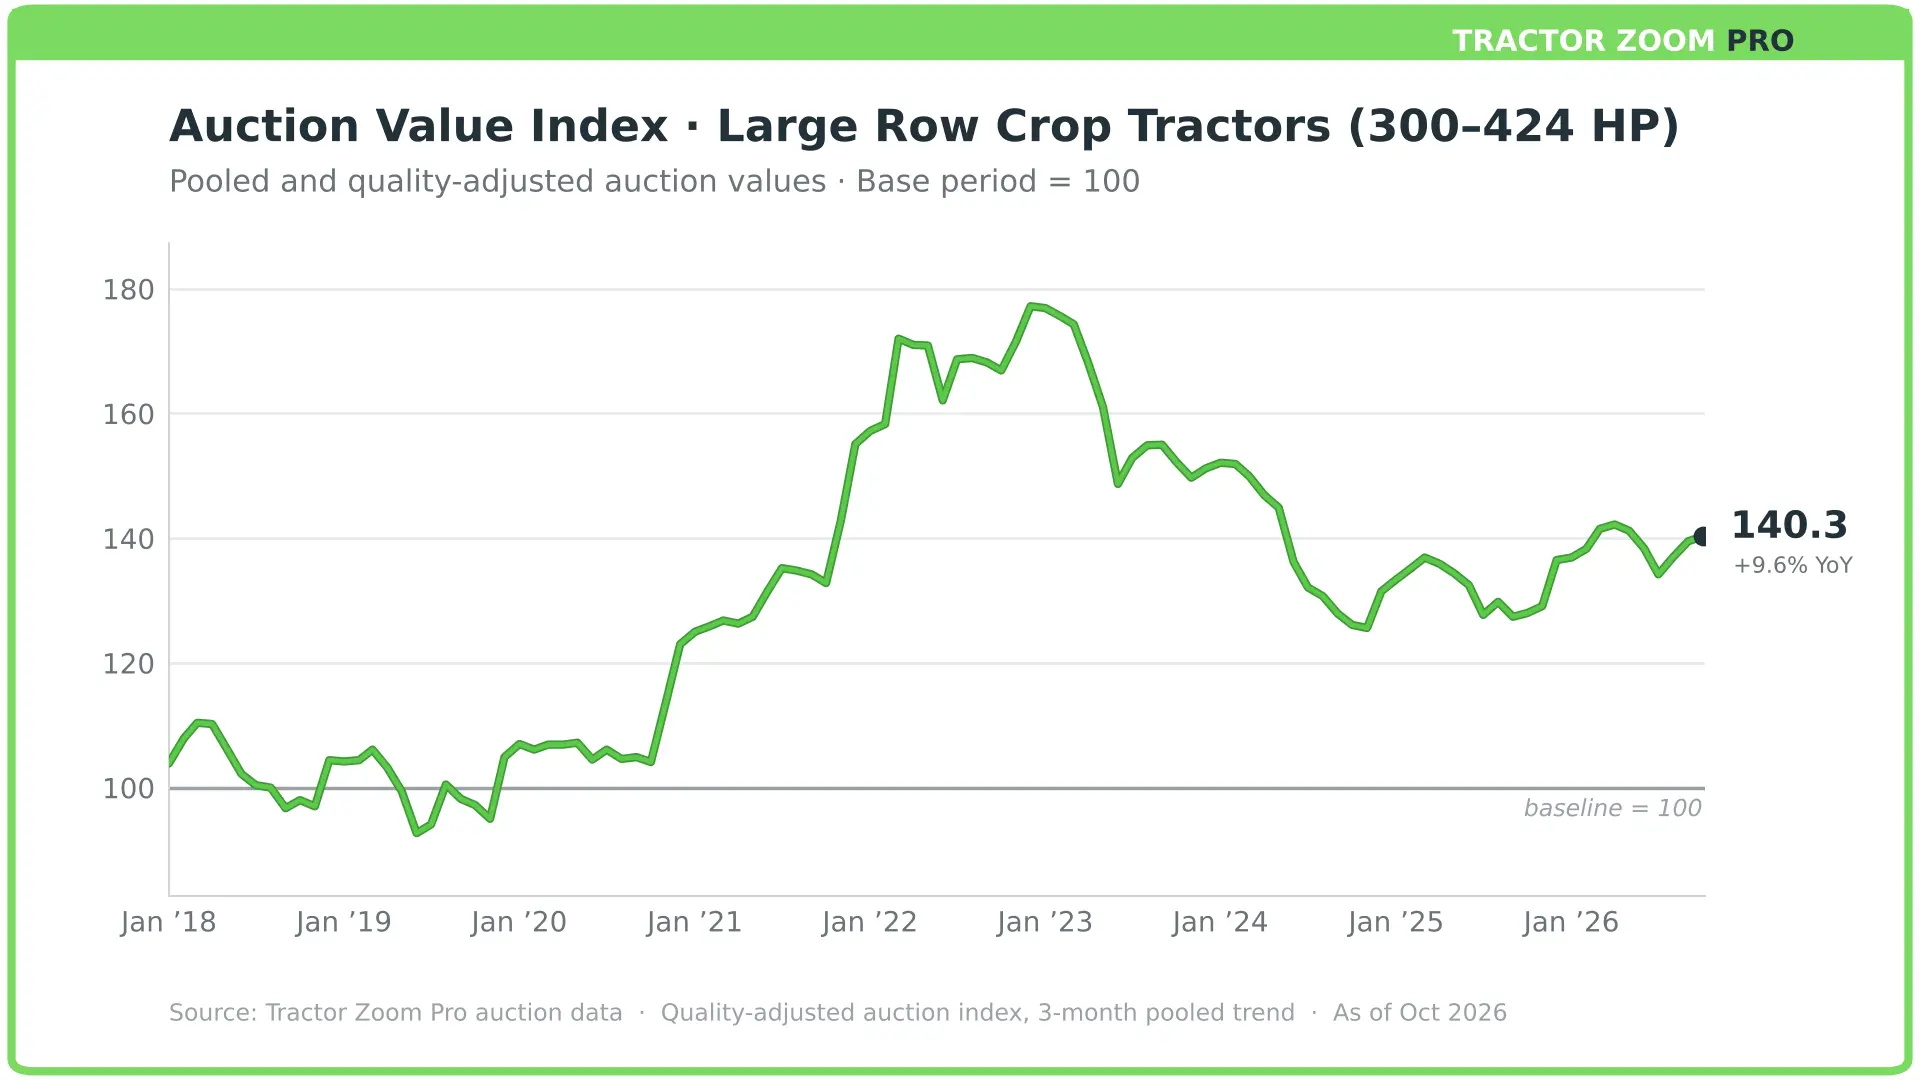
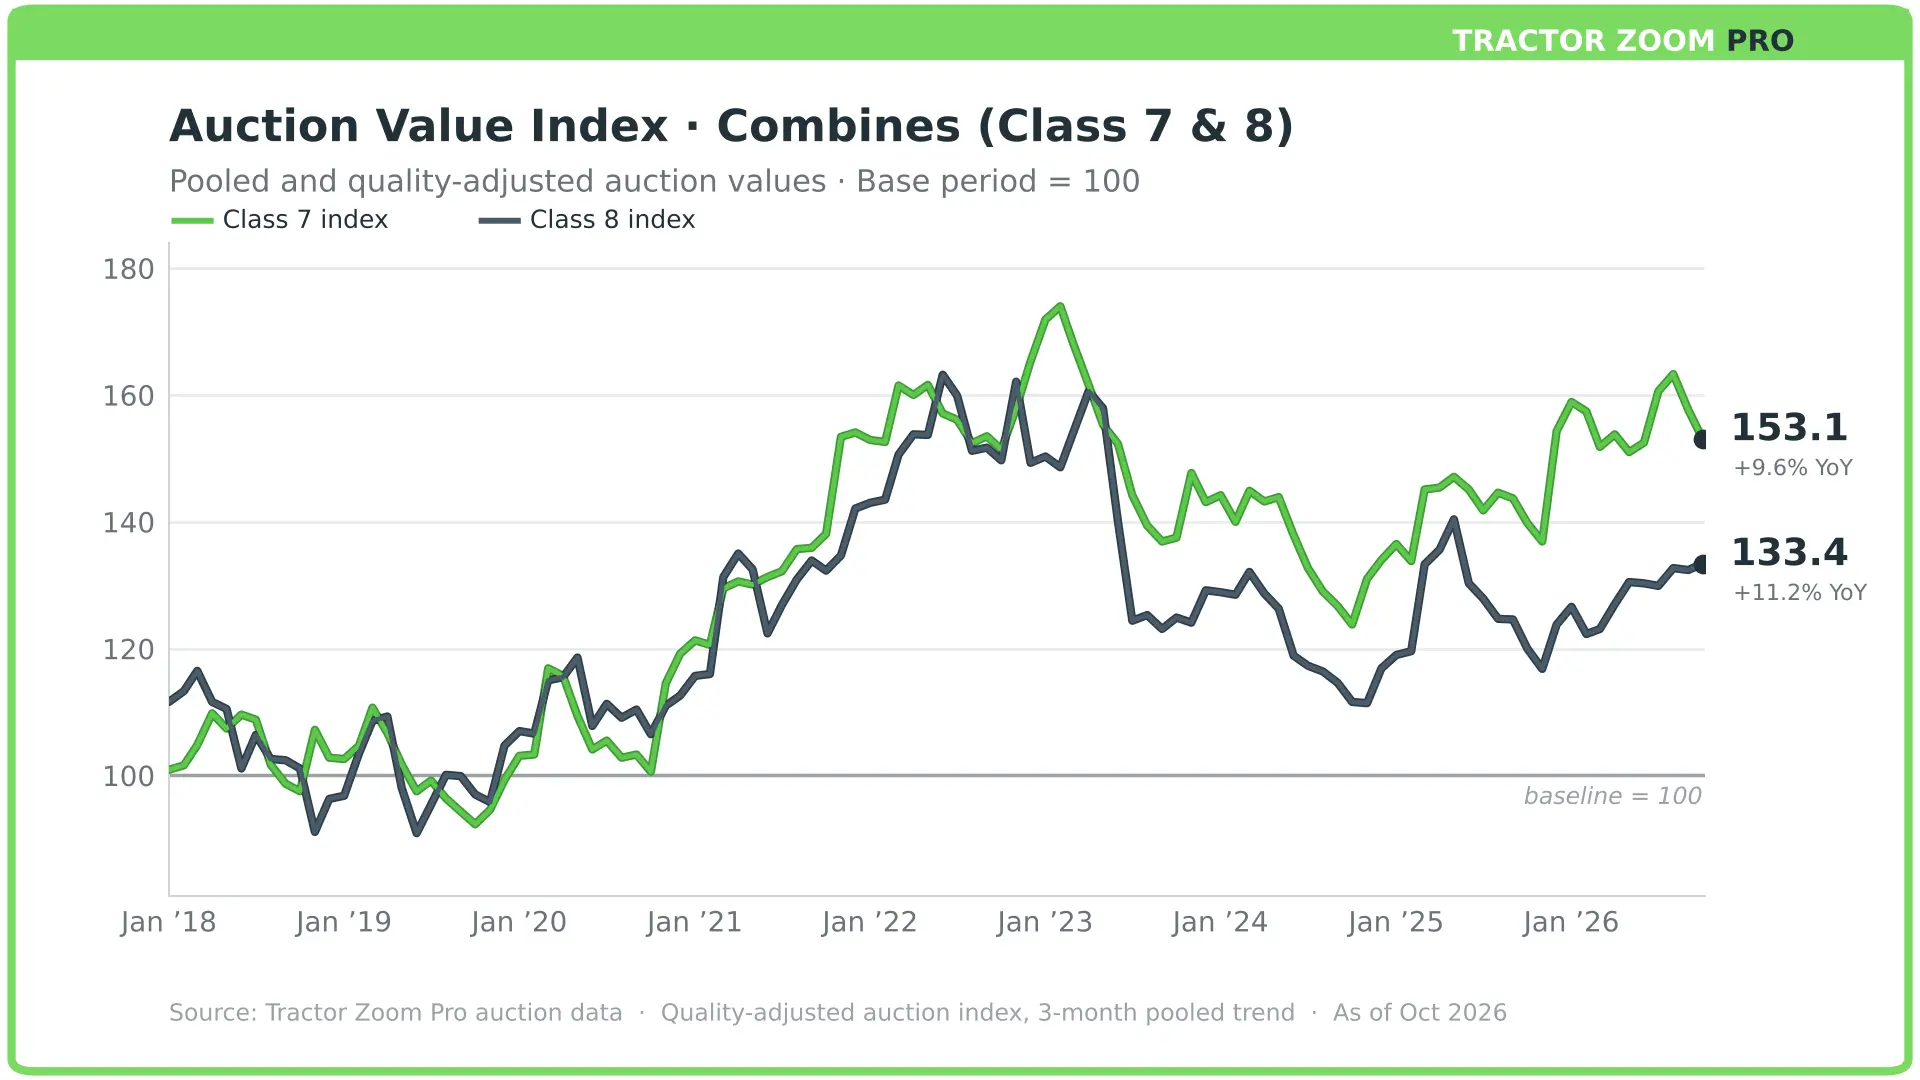
First, the year-over-year inventory difference is balancing. It’s no surprise that inventory has been intentionally dropping, and as recently as last spring most categories were running 25% to 40% below the prior year. By the end of last month that difference has narrowed to single digits in most categories, and Class 7 & 8 combines are now essentially even with last fall. Second, auction values are firming. On our Auction Value Index, every core category we report on is up year-over-year, with small row crop tractors (+12.4% YoY) and Class 8 combines (+11.2% YoY) leading the groups with solid sample sizes.
The takeaway is that supply is rebuilding after harvest the way it usually does, but values have not given anything back yet. Whether they hold through the end-of-year auction season is the question for the next 90 days.
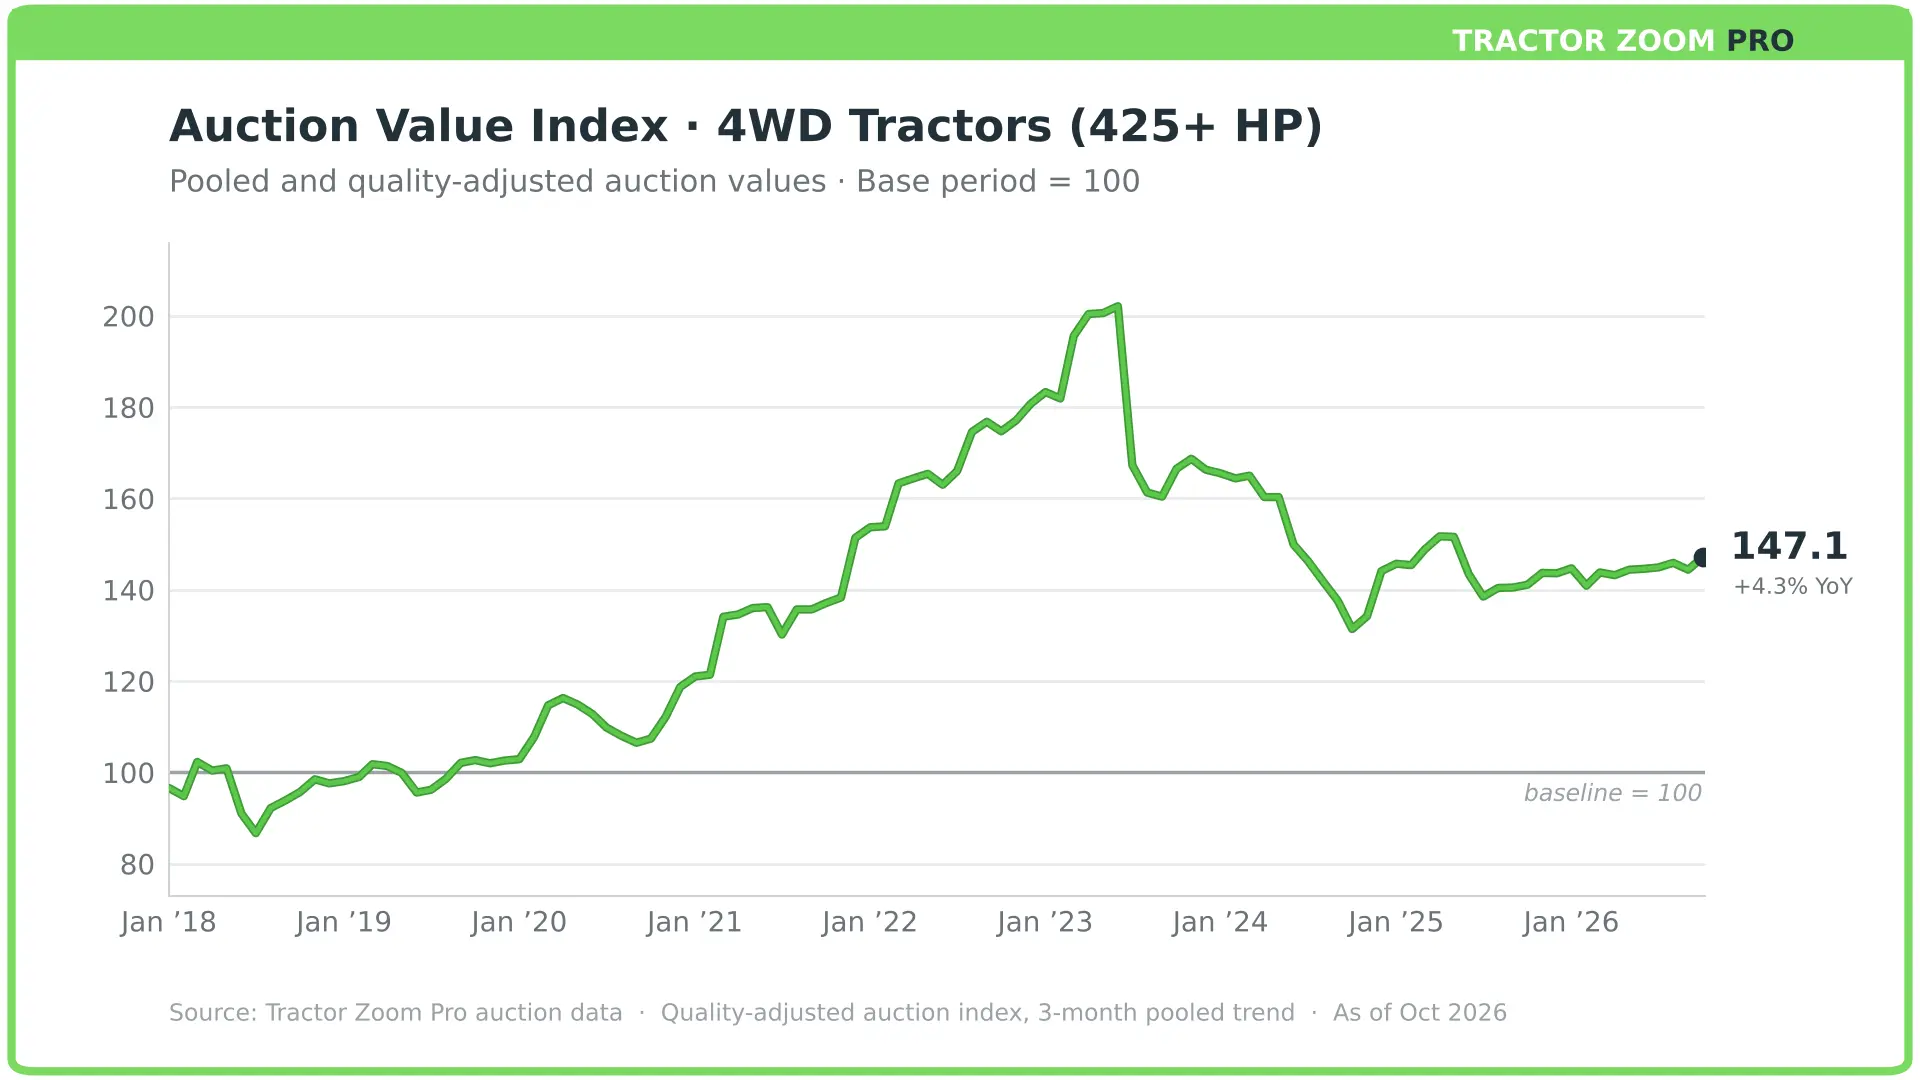
New to the report this month: Auction Value Index graphs. Each equipment category in this report now includes a chart of its Tractor Zoom Auction Value Index going back to 2018 (or to when the index starts for that category). Because the index adjusts for age, size or horsepower, and model series, the line shows how auction values for comparable machines have moved through the 2021 to 2022 run-up, the 2023 to 2024 correction and the recovery since, rather than a simple average of which machines happened to sell in a given month.
Planning for 2027: Wes Davis on the outlook, plus two playbooks
If you make buy-sell, capital or credit decisions, start here before the category numbers. The day after the midterm elections, Andy Campbell sat back down with Meridian Ag Advisors Chief Ag Economist, Wes Davis, on the Beyond the Hood podcast to answer the dealer and lender questions that came out of our fall webinar around corn, rates, tariffs, inputs, land and used equipment.
A few takeaways from the conversation:
- Used values have structural support. Used is taking a bigger share of demand, farmers are running machines longer, and aftermarket tech is keeping older equipment productive. A widening gap between new and used retail prices helps too, and Wes doesn't expect new prices to come down.
- When income improves, debt and used iron come first. Farmers are looking to pay down debt and buy used before they step up to new.
- Rates are a watch item. A possible rate increase around year-end would add pressure on new equipment financing.
- Land is flat to slightly softer, not a 1980s repeat.
Listen to the full episode with Wes Davis on the 2027 ag outlook. And grab the Fall 2026 Playbooks for ag equipment dealers and lenders for a summary of Wes’s insights and practical steps on used inventory, borrower cash flow, collateral and portfolio risk, with scenarios for how the market could break into 2027.
A note on this month's numbers
Every core category below reports five metrics (Inventory Volume, Aged Inventory (360+ Days), 60-Day Sales Velocity, Turn Rate, and the Auction Value Index), each shown year-over-year for October 2026 vs. October 2025 and sourced from Tractor Zoom Pro's dealer and auction marketplace data. The Auction Value Index bullet now also shows the index level itself, so you can see where values sit relative to each category's previous positions.
One pattern runs through the tractor sections. Since January 2025, the months when dealer inventory fell furthest below the prior year are the months when tractor auction values gained the most year-over-year.
Utility tractors (100–174 HP)
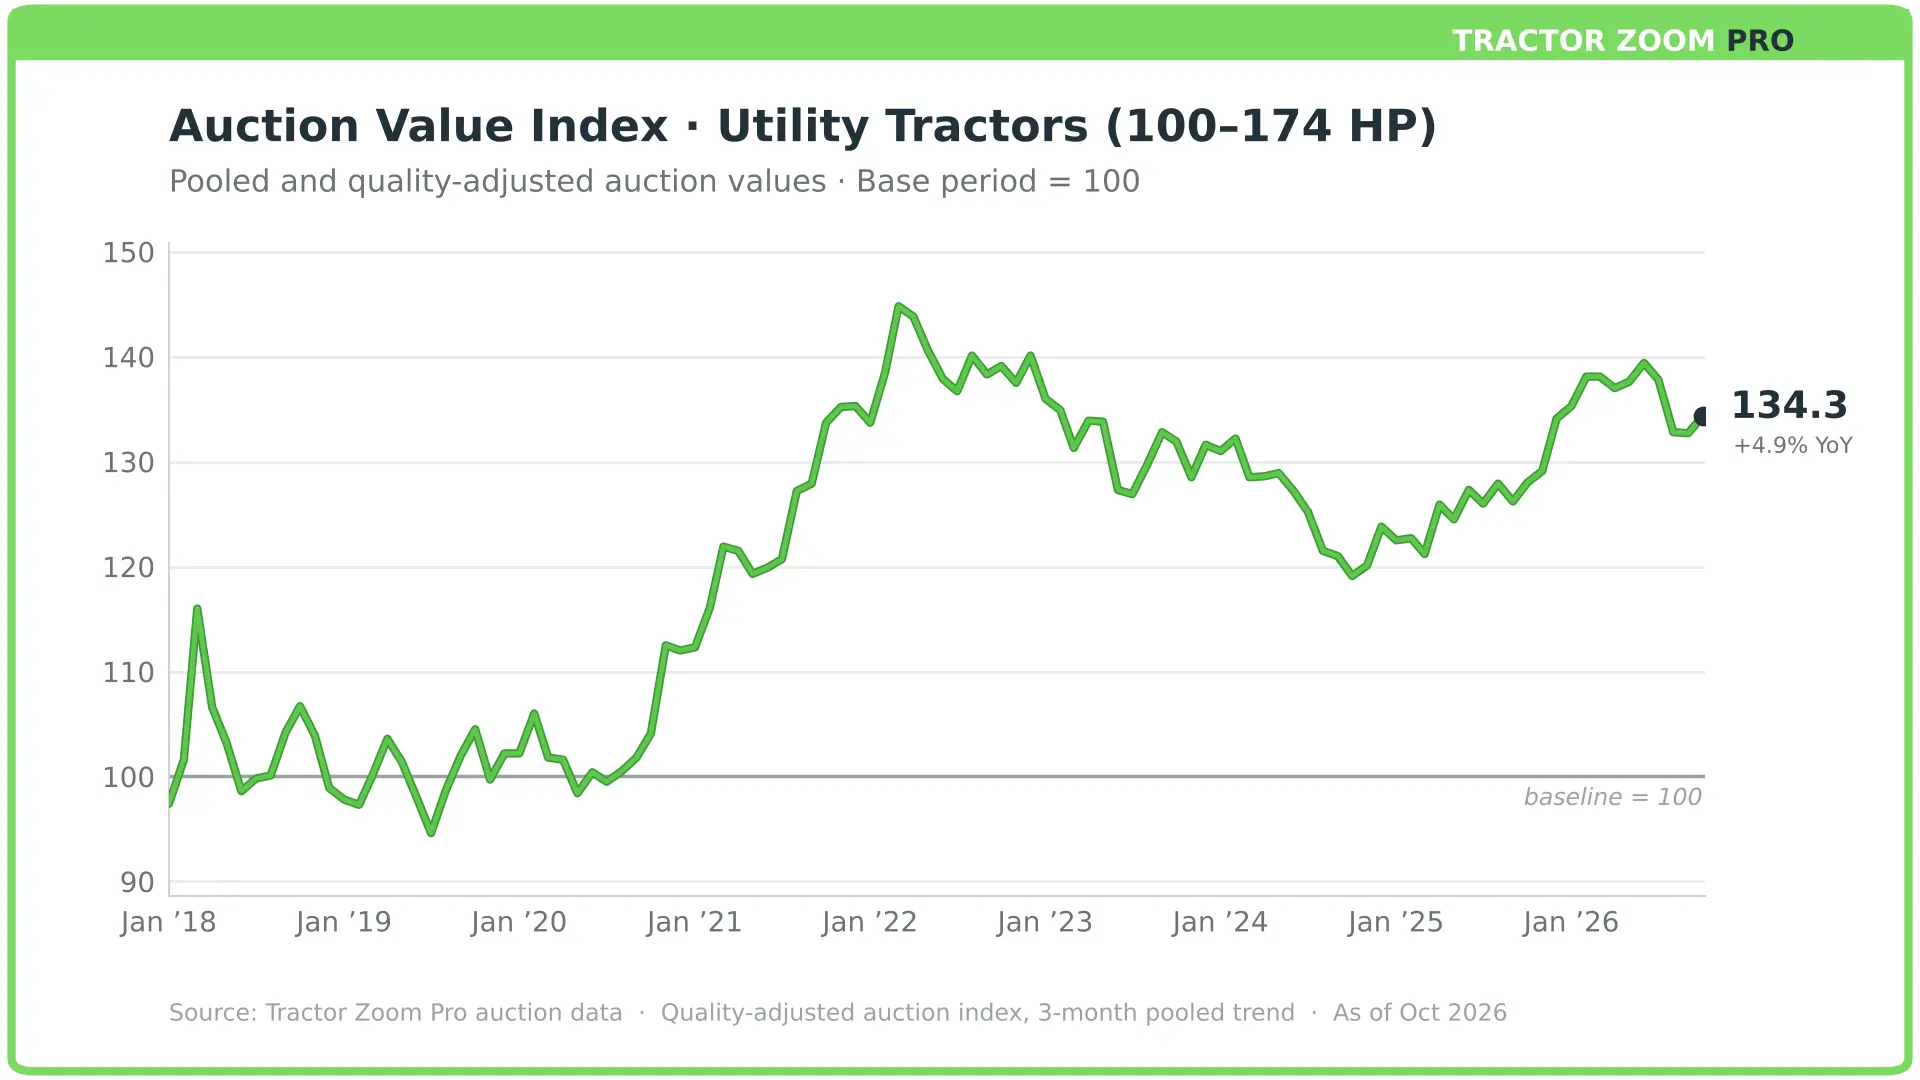
Supply in this class is essentially back to last year's level after running 40% below it in February, and utility tractors show the tightest link between supply and price of anything we track. As inventory fell further below last year through 2025 and 2026, the index climbed almost in lockstep.
At auction, the gains are going to the newer machines. From August through October, utility tractors under 2,000 hours brought a median $53,375, up from $42,250 a year ago, while units over 5,000 hours were flat at about $16,500. With retail turnover at its slowest of the year, low-hour iron is where the money is.
- Inventory Volume: -2.9% YoY
- Aged Inventory (360+ Days): -46.1% YoY
- 60-Day Sales Velocity: -77.3% YoY
- Turn Rate (3-Month Avg.): -53.2% YoY
- Auction Value Index (Pooled): 134.3, +4.9% YoY
Small row crop tractors (175–299 HP)
The strongest value story among the tractors. The index bottomed at 132.6 in October 2025 and has climbed to 149.0 since, a 12.4% gain that still leaves it about 14% below its March 2023 peak. That gain lines up with dealers clearing out their oldest units, with aged inventory down 42%.
At auction the premium is concentrated in low-hour machines: Units under 2,000 hours brought a median $149,000 from August through October versus $105,650 a year earlier, while tractors over 5,000 hours held flat at $32,500. The fleet coming through auction is also getting older (median age 25 years, up from 21), so a clean, low-hour unit stands out.
- Inventory Volume: -10.2% YoY
- Aged Inventory (360+ Days): -41.7% YoY
- 60-Day Sales Velocity: -53.7% YoY
- Turn Rate (3-Month Avg.): -41.8% YoY
- Auction Value Index (Pooled): 149.0, +12.4% YoY
Large row crop tractors (300–424 HP)
This class shows the supply-to-price lag most clearly. Dealer inventory bottomed in April at 28.5% below last year, and the index's year-over-year gain kept building for six months after, reaching +9.6% in October. Values have followed supply by roughly a quarter.
Auction mix tilted newer this fall, with machines five years old or newer making up 23.5% of sales versus 17.1% a year ago. The firming is in low- and mid-hour units: tractors with 2,000 to 5,000 hours brought a median $119,501, up from $96,250, while units over 5,000 hours slipped to $42,000 from $46,000. Even after this year's climb, the index sits about 21% below its December 2022 peak.
- Inventory Volume: -4.9% YoY
- Aged Inventory (360+ Days): -25.7% YoY
- 60-Day Sales Velocity: -70.6% YoY
- Turn Rate (3-Month Avg.): -37.0% YoY
- Auction Value Index (Pooled): 140.3, +9.6% YoY
4WD tractors (425+ HP)
A good example of why we moved to a mix-adjusted index. The raw median auction price for 4WD tractors from August through October was down about 10% from a year ago ($118,000 vs. $131,500). That drop came from fewer late-model units selling, with machines five years old or newer falling from 25.4% of sales to 16.1%.
Compare like for like and values are up: Late-model 4WDs brought a median $383,750 (vs. $315,000), and units over 10 years old brought $96,000 (vs. $81,000). The index captures that at +4.3 YoY%. It also sits 27% below its June 2023 peak, the most ground left to recover of any tractor class, and 60-day velocity fell further than in any other tractor class.
- Inventory Volume: -10.4% YoY
- Aged Inventory (360+ Days): -23.7% YoY
- 60-Day Sales Velocity: -78.7% YoY
- Turn Rate (3-Month Avg.): -29.2% YoY
- Auction Value Index (Pooled): 147.1, +4.3% YoY
Combines (Class 7 & 8)
Combine supply is now even with last fall (-0.6%), but dealers have cleared out their oldest units, with aged inventory down 42%. Unlike tractors, combine values haven't tracked inventory closely over the past two years, so the late-model mix tells you more.
Class 8 shows the mix effect plainly. Its raw median auction price fell to $55,800 from $70,000 as fewer late-model machines came through (five years old or newer dropped from 25% of sales to 18%). On a like-for-like basis values rose: Late-model Class 8s brought a median $310,000 versus $275,000, and the index is up 11.2% YoY. Class 7 is firming at the older end too, with machines over 10 years old bringing a median $43,000, up from $36,750.
- Inventory Volume: -0.6% YoY
- Aged Inventory (360+ Days): -42.2% YoY
- 60-Day Sales Velocity: -29.1% YoY
- Turn Rate (3-Month Rolling Avg.): -24.2% YoY
- Auction Value Index (Pooled): Class 7: 153.1, +9.6% YoY · Class 8: 133.4, +11.2% YoY
Self-propelled sprayers
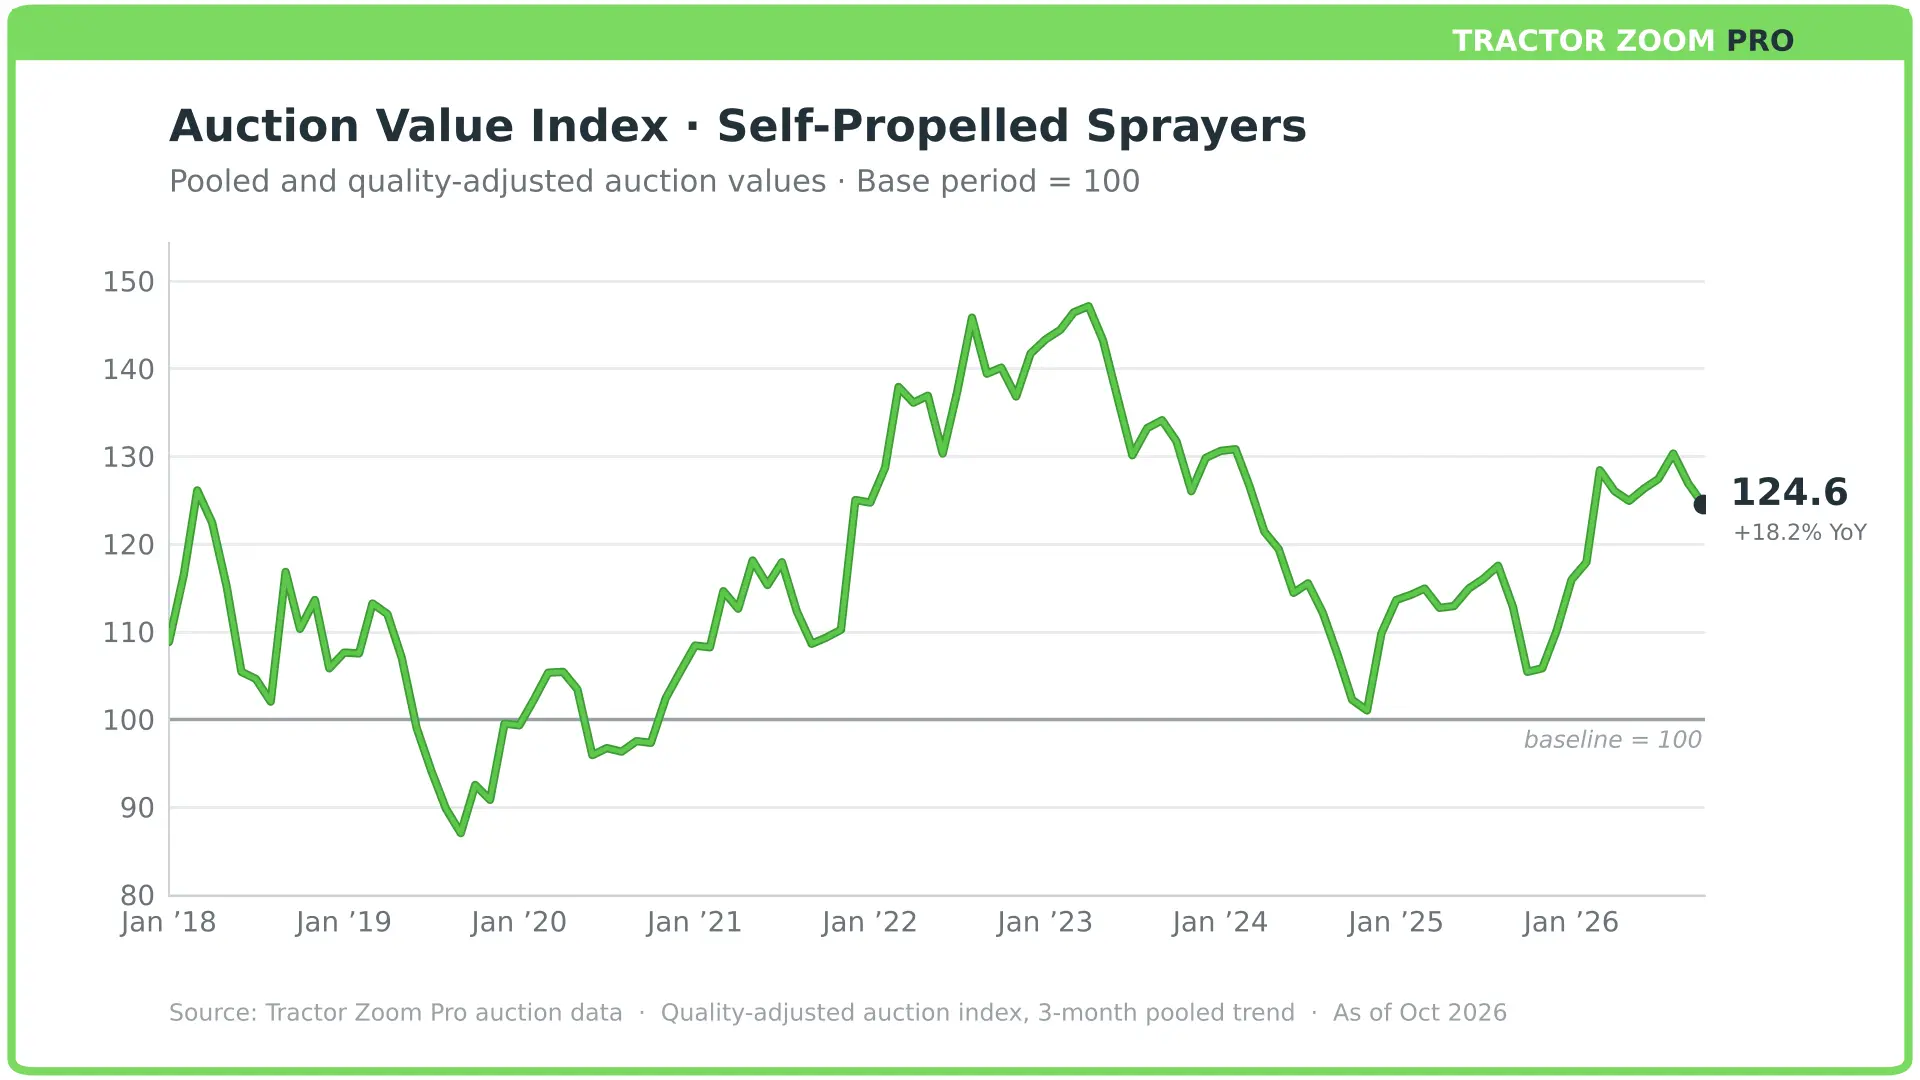
The bifurcated market we've been describing all year shows up clearly at auction. From August through October, sprayers five years old or newer brought a median $261,000, up from $188,000 a year ago, while units over 10 years old rose to $32,800 from $25,500. Both ends gained, but the late-model, tech-equipped machines gained the most.
Read the index's +18.2% with care: it compares against October 2025, the index's lowest reading of the past two years, and rests on only three October sales. On the dealer side, supply is still 7.5% below last year and aged units have thinned by more than a third, but turnover remains soft.
- Inventory Volume: -7.5% YoY
- Aged Inventory (360+ Days): -36.7% YoY
- 60-Day Sales Velocity: -56.8% YoY
- Turn Rate (3-Month Avg.): -40.5% YoY
- Auction Value Index (Pooled): 124.6, +18.2% YoY
Planters
Planters cleared aged inventory faster than any other category this month. Units listed 360+ days are down 53% from last year and now make up about 20% of dealer planter inventory, versus 39% a year ago. Total supply is 8.3% below last year but has been rebuilding, with dealers adding nearly 700 planters to inventory since May, while inventory was essentially flat over the same stretch the previous year.
That fits the early-order and trade-in activity we flagged last month. Turnover is the soft spot, with 60-day velocity down 60% and a turn rate of 0.59, the lowest of any category we track.
We're not reporting a planter Auction Value Index this month while we finish calibrating it. Look for planter index readings in future reports.
- Inventory Volume: -8.3% YoY
- Aged Inventory (360+ Days): -52.6% YoY
- 60-Day Sales Velocity: -60.0% YoY
- Turn Rate (3-Month Avg.): -28.9% YoY
Definitions & data sources
All equipment data and market trends in this report come from Tractor Zoom Pro's dealer and auction marketplace database, which tracks equipment listings, transactions and inventory activity across the U.S. Dealer metrics compare October 2026 with October 2025; auction detail by age and hours compares August through October of each year.
- Inventory Volume: The number of equipment units listed for sale and unsold across the tracked dealer network at month end.
- Aged Inventory (360+ Days): The number of units in inventory that have been listed for 360 days or longer, a measure of iron that is struggling to sell.
- 60-Day Sales Velocity: The number of units that sold during the month within 60 days of their initial listing date. Higher numbers indicate stronger early demand and healthier sell-through.
- Turn Rate (3-Month Rolling Avg.): The average monthly units sold over the past three months, annualized and divided by current inventory. Higher turn rates mean inventory is moving faster.
- Auction Value Index (Pooled): Tracks used equipment prices from auction sales and adjusts for the machine's age and category-specific features (such as horsepower, model series, header width or planter rows), so changes reflect the market rather than the mix of machines that sold that month. The pooled reading is a three-month rolling trend, which smooths out month-to-month swings.
Each category's index is set to 100 at its own base period, so compare year-over-year changes across categories rather than index levels. The index is updated monthly and earlier months may be revised as late auction results come in.
The bottom line
October confirmed the split we've been watching: values are firming while movement stays slow. On our Auction Value Index, every core category is up year-over-year. Where we can compare like for like, the money is going to late-model and low-hour machines, while high-hour iron is flat to soft.
The new wrinkle is supply. Dealer used inventory that ran 25% to 40% below last year this spring is now within about 10% in every category, and combines are back to even. For tractors, values have tracked tighter supply closely over the past two years, so rebuilding inventory is the first thing that could cool them. Watch the winter auction season: If values hold while lots fill back up after harvest, that's a sign the floor is real. As Wes Davis noted on the podcast, when income improves, farmers tend to buy used before new, and that's the demand this market is waiting on.
Have you accessed sold data within Tractor Zoom Pro yet? It takes minutes to set up and gives you access to the real-time comps driving these decisions. If you're already a Tractor Zoom Pro user, reach out to your Customer Success Manager to make sure you have access to this data source.
To get market insights like these delivered to your inbox each month, sign up for our free newsletter.
Join the future of ag & heavy equipment sales
Take a guided tour of Tractor Zoom Pro and Anvil Pro to discover how wider margins and faster turns are just a few clicks away.